Financial Services Marketing Automation: Scaling Local Marketing Without Scaling Compliance Risk

Share


Summary
- Financial services marketing automation refers to the systems, workflows, and agents that execute local marketing across every branch, advisor, and agency without requiring manual work at each one.
- Local SEO in financial services carries a constraint no other vertical shares at the same intensity: every public-facing message has to satisfy compliance review, which is precisely what makes manual execution unscalable.
- AI agents, specifically SOCi’s Genius Agents, execute location-level work autonomously inside brand and compliance parameters, removing the tradeoff between speed and control.
- Institutions that cannot automate local marketing lose visibility in exactly the moments that matter most, when a consumer is searching for a nearby branch, advisor, or agent and choosing on trust signals alone.
- SOCi’s 2026 Local Visibility Index finds that brands using AI-driven local marketing achieve clearly higher local search visibility than brands managing locations by hand.
In financial services local marketing, the post most likely to clear compliance review is often the one least likely to help a branch rank. It’s generic enough that nobody has to discuss it, which also makes it generic enough that Google has no reason to show it to anyone.
That matters because financial decisions are still made close to home. Someone looking for a mortgage, a small-business checking account, or an insurance policy searches nearby, reads reviews, and decides who seems trustworthy before walking in or calling. Those judgments are formed on Google, maps, and review sites, based on how complete a profile is, how accurate its details are, what its rating is, and whether the institution responds to reviews.
Most institutions handle this by routing every piece of local content through the same approval queue. That keeps the institution safe, but it limits local marketing to whatever the queue can handle. This post looks at why that trade-off exists, where it hurts most, and how AI agents working inside compliance guardrails change it.
What Is Financial Services Marketing Automation?
Financial services marketing automation is the use of systems and AI-driven workflows to execute, monitor, and optimize local marketing across branches, advisors, and agencies without manual effort at each location. The goal is locally relevant, brand-compliant, review-ready output at every point of presence, produced at a volume central marketing and compliance teams cannot reach by hand.
It spans several operational domains:
- Listings and citation accuracy: Keeping NAP data, lobby and drive-through hours, and service details consistent across every directory and map surface, and updating them when branches consolidate, relocate, or change hours.
- Google Business Profile optimization: Publishing location-specific posts, maintaining service attributes and accessibility details, and managing photos and Q&A for every branch, office, and advisor profile.
- Reputation management: Monitoring review streams, responding in approved language that avoids any discussion of individual accounts, and flagging locations where service issues are surfacing publicly.
- Local content publishing: Distributing genuinely localized content to social profiles, local pages, and listing platforms within approved messaging boundaries.
- Performance monitoring by location: Tracking local visibility, discovery, and engagement per branch or advisor so declines are caught before they show up in local deposit, loan, or policy volume.
What sets it apart from automation in other industries is that every output has to hold up under compliance review. Pushing one approved corporate post to 400 profiles checks that box, but it does nothing for any individual branch’s local search ranking.
The Compliance Paradox
Compliance review exists for good reasons, and nobody is arguing it should go away. The problem is the way it’s usually applied to local marketing: item by item, through a queue with limited capacity. That creates a predictable chain of effects.
- The queue sets the pace. Review capacity, not writing capacity, determines how much local content gets published. Most branches and advisors end up with little or nothing.
- Speed pushes content toward generic. Content written to get through review quickly avoids anything specific, and specific local detail is exactly what Google rewards.
- Local voice gets locked out. Branch managers and agency owners want to speak to their communities. Corporate needs message discipline. Without a way to enforce limits automatically, institutions lock everything down and lose local relevance.
The tools most institutions use don’t resolve this, because they were built around the queue:
- Approval routing is mistaken for automation. A tool whose main job is routing content for review has automated the review, not the marketing. Someone still has to create every piece.
- Rules can’t handle exceptions. A branch closes for a system conversion. A rate change requires updated disclosures. An advisor moves to a new territory. If-then rules can’t handle these, so each one waits for a person who is already busy with the approval queue.
- Dashboards stop at reporting. Dashboards show which branches are losing local visibility. Fixing each one still requires diagnosis, approval, and execution, and at 500 locations plus advisor profiles, that doesn’t scale.
- The stack is fragmented. Google Business Profile, directories, social, review sites, and branch and advisor pages are usually managed in separate tools, with no single view of local performance.
Two Footprints: Branches and the People in Them
Financial services has something most multi-location businesses don’t: two kinds of local presence that consumers search for. People look for a nearby branch, and they also look for a specific advisor, loan officer, or insurance agent by name. Both need accurate profiles, and advisor profiles can multiply an institution’s local footprint well beyond its branch count. Institutions that manage only branch profiles miss a large share of high-intent local searches.
Both footprints change constantly. Branches consolidate, relocate, and adjust lobby and drive-through hours. Advisors change territories or leave for other firms, and their profiles either move with them or are left behind. Every change has to reach dozens of listing sites. SOCi’s Local Visibility Index found that while 98% of brand locations studied had claimed their Google profile, only 80% had claimed Yelp and only 53% were managing Facebook pages, and that inconsistencies like these leave LLMs citing local brand information correctly only about 79% of the time.
In most industries, a wrong phone number is a lost lead. In financial services, where consumers are checking whether an institution is legitimate, a wrong phone number or outdated address also raises doubts about trust.
Review Responses: Where the Stakes Are Highest
Financial institutions receive fewer reviews than restaurants or retailers, but each response carries more risk. A 300-branch institution averaging 6 reviews per branch each month receives 1,800 reviews a month. With drafting and review, each response takes about 12 minutes, which comes to 360 hours of work every month. As a result, most institutions answer only a fraction of their reviews, and unanswered reviews weaken local signals in a category where a rating stands in for trust.
A compliant response has to do several things at once:
- Acknowledge the specific issue the reviewer raised, such as a long wait, a confusing fee, or a helpful teller.
- Never confirm or discuss whether the reviewer has an account or relationship with the institution.
- Follow the institution’s approved compliance guidelines and all applicable local, state, and federal requirements.
- Avoid anything that could be read as financial advice or a promise about an outcome.
- Offer a private way to follow up.
- Still sound like a person, not a legal disclaimer.
Doing all of that consistently, by hand, across hundreds of locations is what most institutions can’t staff. Falling back on a generic reply isn’t much safer, because a canned response to a specific complaint can hurt more than silence.
From Reviewing Every Post to Setting the Rules of Financial Services Marketing Automation
AI agents change the equation because they can make location-specific judgment calls within defined boundaries. Compliance moves from checking each item after it’s written to defining the rules that shape it as it’s written. Here’s how that changes day-to-day work:
| Task | Item-by-Item Approval | Guardrails Set by Compliance |
|---|---|---|
| A local branch post | Drafted centrally, queued for review, often simplified to pass quickly, then pushed to every branch | Written for each branch within approved topics and language; anything outside the rules goes to a reviewer |
| A review response | Waits for someone to draft and approve it, or gets a generic template | Written to the specific issue in approved language, with no account details or advice |
| An hours change | Updated manually on some listings, missed on others | Updated across every listing and monitored for drift |
| An exception | Lands in a queue behind routine approvals | Flagged and routed to the right person, while routine work continues |
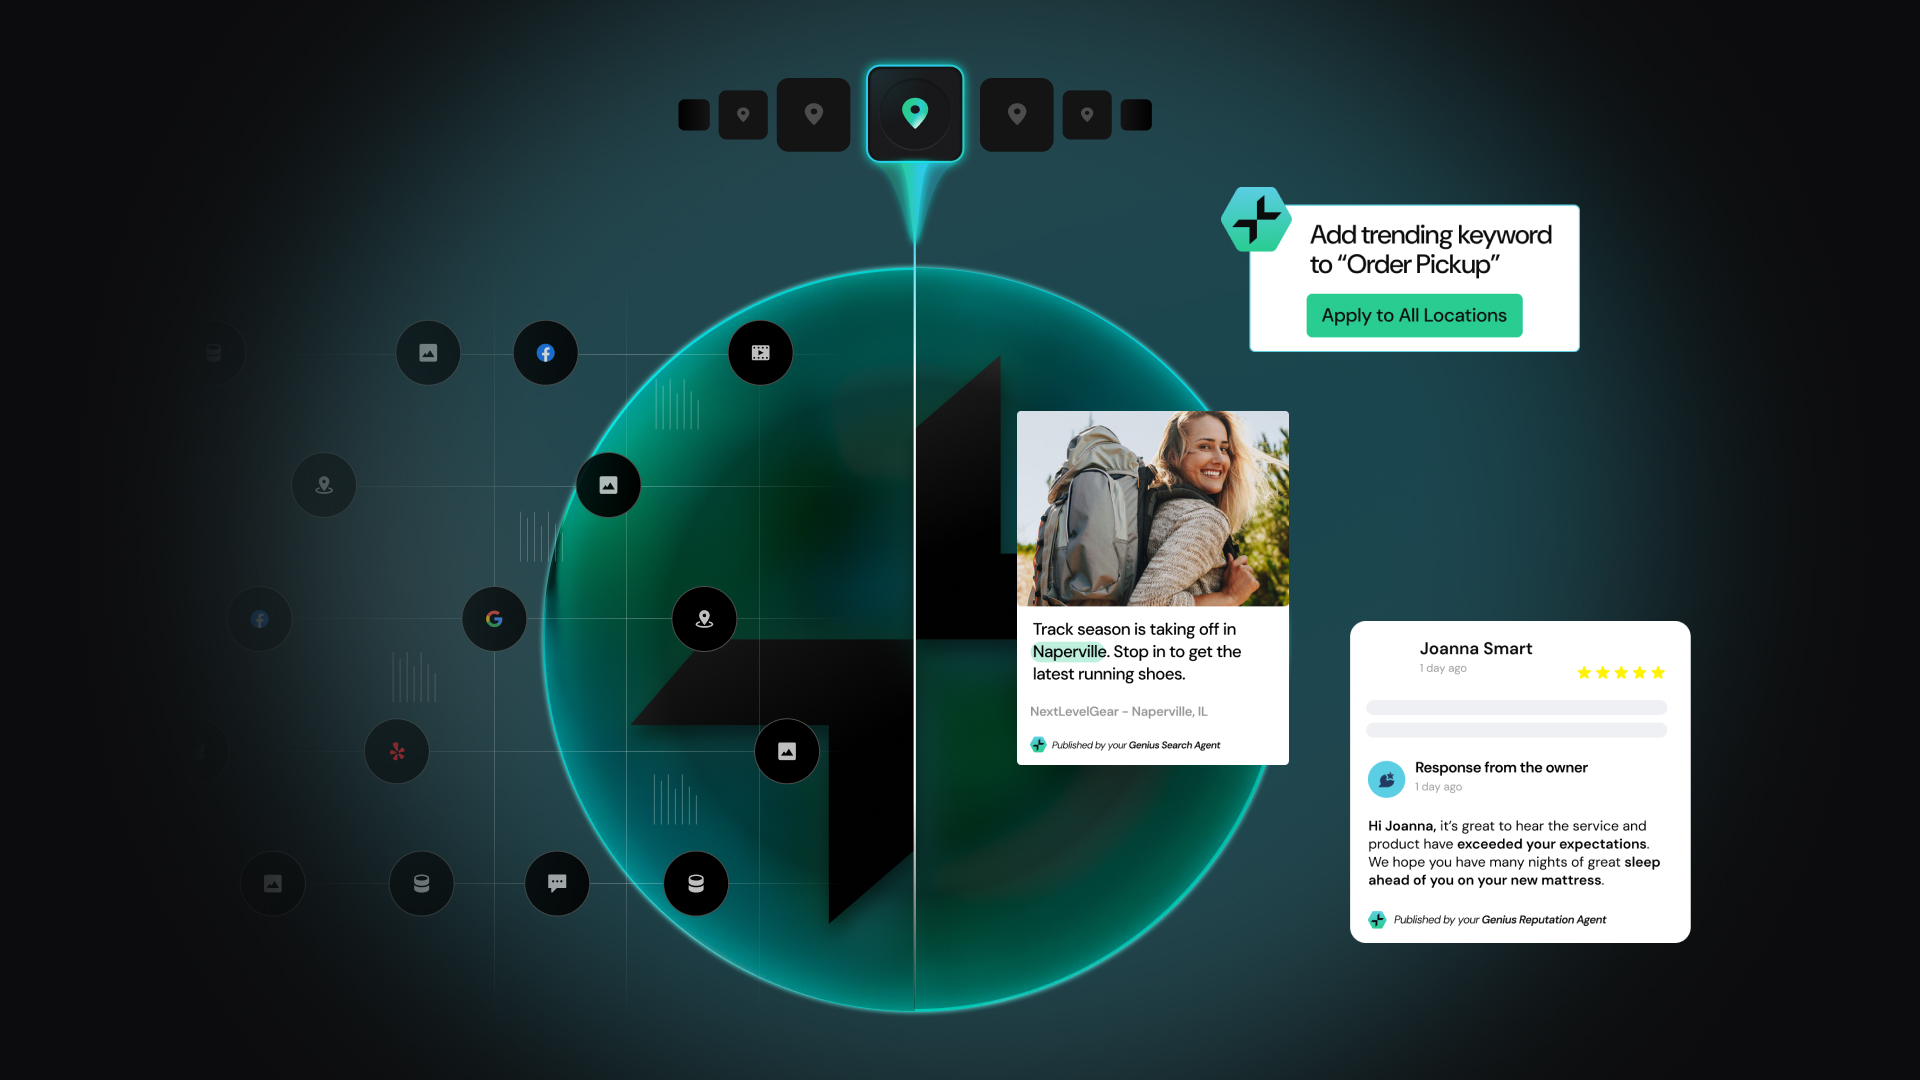
SOCi’s Genius Agents are that shift in practice. The Local Search Agent maintains profile and service accuracy across branches and advisor profiles and publishes location-specific updates. The Social Agent produces locally calibrated content within approved messaging boundaries. The Reputation Agent responds to reviews in approved language matched to what the reviewer raised, without straying into account specifics. Marketing and compliance set the parameters. The agents operate inside them and escalate exceptions.
The agents also work in a continuous loop, monitoring every branch and advisor profile, spotting locations that are falling behind, identifying the likely cause, and acting within the rules. Local visibility becomes an ongoing operation instead of an annual initiative, and institutions get the equivalent of a dedicated local marketer at every location without adding headcount at each one.
Questions to Ask When Evaluating a Financial Services Marketing Platform
Most institutions today either approve and push a limited set of content from corporate or use a platform to route approvals and manage exceptions. Few have reached the point where location-level work runs inside guardrails on its own. When evaluating platforms, bring your compliance team to the conversation and ask these four questions:
- Where are the rules enforced? Ask how brand and compliance boundaries are applied when content is created, not just when it’s reviewed. Enforcing them upfront is what makes volume possible.
- How is content made for one branch or advisor? Ask for a specific example. If the answer is a template with the branch name filled in, it isn’t AI-driven local marketing.
- What do review responses look like under real constraints? Ask for sample responses to real reviews. They should address the specific issue without mentioning account details or offering anything that looks like advice.
- Does it cover advisors as well as branches? Consumers search for both. A platform that manages only branch profiles leaves much of your local search presence uncovered.
The payoff is measurable. SOCi’s industry research shows that brands managing Google Business Profile optimization as an integrated, automated workflow, rather than a periodic manual task, see a 14% lift in visibility.
Advancing Financial Services Local Marketing Maturity
Most institutions sit somewhere on a curve running from fully manual to fully agentic. Moving up requires operational redesign, and usually a redefinition of what compliance reviews.
Stage 1: Location-dependent. Branches and agencies manage their own profiles inconsistently. Brand and compliance risk is highest here, and corporate has no visibility.
Stage 2: Centralized lockdown. Corporate approves and pushes a limited set of content to every profile. Risk drops. Local relevance drops with it. Profile performance is weak because the content is generic.
Stage 3: Platform-assisted management. A platform aggregates location data, centralizes review monitoring, and routes content for approval. Human teams manage exceptions. Performance improves, but it scales with headcount and with compliance capacity.
Stage 4: Agentic execution. Genius Agents execute location-level work autonomously inside brand and compliance parameters. Marketing and compliance focus on parameter design, exception review, and interpretation. Local search ranking improves as a byproduct of continuous operation.
Stage 4 is where Genius Agents operate. Most financial institutions are in Stage 2 or 3.
Frequently Asked Questions
What is financial services marketing automation? Financial services marketing automation is the use of software systems and AI-driven workflows to execute, monitor, and optimize local marketing across branches, advisors, and agencies without manual intervention at each location. It covers listings accuracy, Google Business Profile optimization, review response, local content publishing, and location-level performance monitoring.
How do AI agents work within compliance requirements? Genius Agents operate inside brand-defined and compliance-defined parameters set by the institution. Rather than generating content and sending it into a review queue, the boundaries are enforced at generation, and anything outside them is escalated for human review. That changes compliance from an item-by-item bottleneck into a governance function.
Why is local SEO different for financial services? Consumers evaluate financial providers on trust signals before contact: profile completeness, accuracy, rating, and whether the institution responds to reviews. Those signals also drive local ranking, so the same factors that build consumer confidence determine whether a branch appears in near-me search at all.
Should institutions manage advisor-level profiles as well as branch profiles? Yes. Consumers search for named advisors and agents as well as branches, and advisor-level profiles substantially expand the local footprint. Managing only branch profiles leaves a significant share of high-intent local search uncovered.
What is the Local Visibility Index and why does it matter for financial services? The Local Visibility Index is SOCi’s annual research benchmarking local marketing performance across multi-location brands and industries. It reports on profile optimization rates, review response rates, local search visibility, and competitive performance by sector, which gives financial marketers external benchmarks for the internal business case.
Where should a financial institution start? Start with Google Business Profile completeness and accuracy across every branch and advisor profile. Verify NAP consistency across major directories next, since accuracy doubles as a legitimacy signal in this category. Then focus on review response rate, a confirmed local ranking factor. Automating those three before expanding into local content produces the fastest measurable improvement.
See Our Genius Agents In Action
See how SOCi Genius Agents automate local marketing across every branch, advisor, and agency in your network.
Related Articles